How to Use a Virtual Card for Safer Online Payments
Shopping online is convenient, but entering payment information on unfamiliar websites can raise security concerns.
Whether you’re purchasing clothing, booking a service, or subscribing to a digital platform, protecting your financial details should be part of every online transaction.
One payment option worth understanding is the virtual card.
Virtual cards allow eligible customers to make payments using digital card credentials. Depending on the provider, they may also offer spending limits, temporary numbers, or additional security controls.
But are virtual cards actually safer than traditional payment cards? And how can you use one for online purchases?
This guide explains how virtual cards work, their advantages and limitations, and the steps you can take to protect your payment information.
What Is a Virtual Card?
A virtual card is a digital payment card that can be used without presenting a physical plastic card.
It typically includes payment credentials such as a card number, expiration date, and security code.
Some virtual cards are linked to an existing credit or debit account, while others are issued as separate digital payment products.
The PCI Security Standards Council recognizes issuer-generated virtual card numbers as a type of credential that can help reduce payment risks in particular situations.
However, virtual card products do not all operate in the same way.
Some use a reusable card number, while others generate credentials designed for a specific transaction or merchant.
The features available depend on your financial institution and the card programme.
How Does a Virtual Card Work?
When you use a virtual card, a payment provider authorizes a transaction using digital payment credentials.
Depending on the product, those credentials may be linked to an underlying account or funded balance.
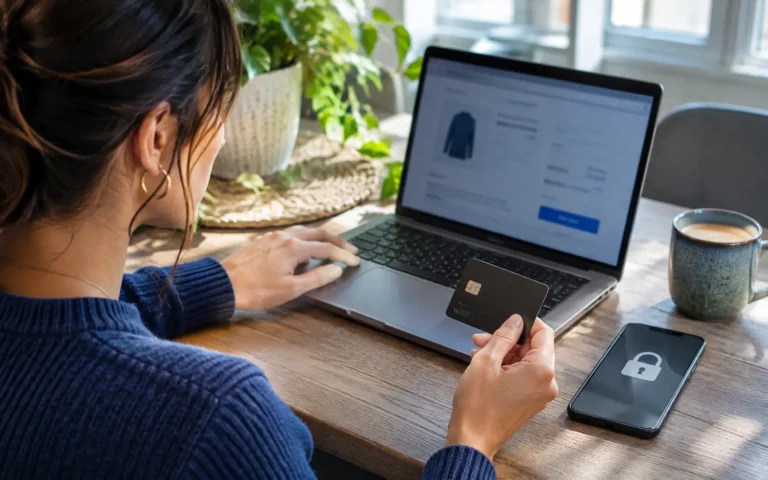
For a typical online purchase, you select an item, proceed to checkout, and enter your virtual card information.
The merchant processes the payment through its supported card network or payment provider.
If the transaction is approved, the amount is charged according to the terms of your card.
Virtual Card vs. Physical Card
| Feature | Virtual card | Physical card |
|---|---|---|
| Card format | Digital credentials | Plastic or other physical card |
| Online purchases | Usually supported | Usually supported |
| In-store payments | Depends on digital wallet compatibility | Typically supported |
| Card number controls | Available with some providers | Less commonly available |
| Spending limits | Provider-dependent | Provider-dependent |
| ATM withdrawals | Often unavailable | Available on eligible cards |
| Replacement after exposure | May be faster digitally | May require card replacement |
Neither type of card is automatically safe from every form of fraud.
A virtual card’s advantages depend on the specific security features it provides.
How to Use a Virtual Card for Online Shopping
Getting started usually involves a few straightforward steps.
Step 1: Check Whether Your Provider Offers Virtual Cards
Open your financial institution’s official website or banking application.
Look for options such as “Virtual Card,” “Digital Card,” or “Create Card.”
Some banks include virtual card functionality within existing accounts, while others offer separate products.
Availability varies by country, institution, and account type.
Step 2: Create or Activate Your Virtual Card
Follow the instructions provided by your bank.
You may need to confirm your identity or approve the action using an existing authentication method.
Once activated, eligible customers can usually view the digital card credentials in a secure area.
Step 3: Review Available Security Controls
Depending on your provider, you may be able to:
- Set spending limits.
- Temporarily freeze the card.
- Create a card for a specific merchant.
- Generate temporary payment credentials.
- Receive transaction notifications.
Not every virtual card includes these features.
Before shopping, review the controls available on your particular product.
Step 4: Make Your Online Purchase
Visit a trusted online retailer and select the product you want.
At checkout, choose card payment if supported.
Enter the virtual card number, expiration date, and security code when required.
Complete any additional bank verification requested through an official authentication channel.
Step 5: Save Your Purchase Confirmation
Keep the receipt, order confirmation, transaction reference, and merchant contact information.
These records may be useful if you need to request a refund or dispute an unexpected charge.
Are Virtual Cards Safer Than Physical Cards?
Virtual cards can provide an additional layer of protection, particularly when they use credentials separate from your main card number.
For example, if a merchant-specific virtual card number becomes exposed, the compromised credentials may have more limited usefulness outside that merchant.
Similarly, a single-use number may reduce the opportunities for subsequent unauthorized transactions after its permitted use.
However, these benefits depend on how the product is implemented.
A reusable virtual card without spending controls may still be vulnerable if its details are stolen.
Virtual cards also do not prevent every type of online fraud.
A scammer may still persuade someone to authorize a payment, and a fraudulent merchant may still fail to deliver a purchased product.
The main benefit is reducing exposure or controlling use of payment credentials, not eliminating financial risk.
Types of Virtual Cards Explained
Different virtual card products are designed for different situations.
| Type | Common purpose | Important limitation |
|---|---|---|
| Reusable virtual card | Repeated online purchases | Credentials may remain usable if exposed |
| Single-use virtual card | One-time transactions | May not suit recurring payments |
| Merchant-locked card | Purchases from one retailer | Availability and merchant recognition vary |
| Virtual debit card | Spending from linked funds | Account balance and fees still matter |
| Virtual credit card | Purchases using available credit | Interest and repayment obligations may apply |
| Prepaid virtual card | Spending from a funded balance | Reloading, acceptance and refund restrictions may apply |
These categories are illustrative. Individual products may combine several features or use different terminology.
Virtual Cards and Digital Wallets: Are They the Same?
Virtual cards and digital wallets are related, but they are not identical.
A virtual card is a set of digital payment credentials issued or managed through a financial provider.
A digital wallet is a service that can store payment methods and support electronic transactions.
Some digital wallets use payment tokenization, which replaces sensitive card details with alternative credentials during supported transactions.
Mastercard, for example, describes its Click to Pay service as using virtual card numbers to protect payment information during checkout.
However, adding a card to a digital wallet does not necessarily create a separate virtual card number that users can view or manage.
Always check which security features your chosen service actually provides.
Can You Use a Virtual Card for Subscriptions?
Some virtual cards support recurring payments for streaming services, software subscriptions, and other memberships.
Others are designed for single purchases and may not work for automatic renewals.
Before using a virtual card for a subscription, confirm that recurring payments are supported.
A merchant-specific card may be useful for tracking payments to one subscription provider.
However, disabling a virtual card does not necessarily cancel the subscription contract.
You may still owe payment under the agreement.
To cancel a subscription, follow the merchant’s official cancellation procedure and keep confirmation of your request.
How Much Does a Virtual Card Cost?
Some financial institutions provide virtual cards without additional issuance charges.
Others may apply fees depending on the account or service.
Potential costs include account maintenance fees, card creation charges, foreign transaction fees, currency conversion costs, and borrowing interest for credit-based products.
Example: Comparing Payment Costs
Imagine purchasing an item worth 100 currency units.
| Payment detail | Card A | Card B |
|---|---|---|
| Purchase price | 100 | 100 |
| Hypothetical transaction fee | 0 | 3 |
| Total charged | 100 | 103 |
This example is hypothetical and does not represent actual products or market pricing.
A virtual card offering more security controls is not necessarily the cheapest option.
Compare the total cost, including relevant fees, before choosing a provider.
What Happens if a Virtual Card Payment Is Declined?
A declined virtual card transaction can happen for several reasons.
The payment may exceed the available balance, credit limit, or a custom spending restriction.
The card may have expired, been frozen, or reached a usage limit.
Some merchants may also reject certain prepaid or temporary card products.
If your payment fails, review the card status and transaction details through your official banking application.
Avoid repeatedly submitting payment information to an unfamiliar website when the reason for the decline is unclear.
If necessary, contact your provider using an official support channel.
What Happens to Refunds on Virtual Cards?
Refund procedures depend on the merchant and card issuer.
In many cases, a refund can be credited to the underlying account even when a temporary virtual card number has expired or been disabled.
However, this is not guaranteed for every product.
Some prepaid or single-use card services may have additional restrictions.
If you are expecting a refund, keep the original transaction reference and contact your provider for instructions.
Do not assume that deleting a virtual card automatically prevents a refund, or that the refund process will work identically across providers.
7 Practical Tips for Safer Virtual Card Payments
A virtual card is most effective when combined with responsible online security habits.
1. Use official banking applications. Download financial applications only through trusted sources and verify the provider.
2. Enable transaction notifications. Alerts can help you identify unexpected charges quickly.
3. Protect account access. Use strong, unique passwords and multifactor authentication where available.
4. Review the retailer before purchasing. Check its contact details, independent reviews, and refund policy.
5. Set sensible spending controls. Where supported, choose limits appropriate to your planned purchases.
6. Never share verification codes. Legitimate transaction authentication should happen through approved channels, not through unsolicited messages.
7. Monitor statements regularly. Report suspected unauthorized activity promptly.
The US Federal Trade Commission also advises online shoppers to investigate sellers and retain purchase records.
These precautions remain important even when virtual payment credentials are used.
Important Considerations
Virtual cards are not available through every financial institution or in every country.
Features such as temporary card numbers, card locking, merchant restrictions, and digital wallet integration vary widely.
Consumer protections and dispute rights also depend on local laws, card networks, and issuing institutions.
A virtual card does not guarantee that a merchant is legitimate or that a transaction can always be reversed.
The presence of HTTPS indicates that a website uses an encrypted connection, but it does not prove that the seller is trustworthy.
Be cautious of unfamiliar services claiming to offer anonymous or completely fraud-proof payment cards.
Before opening an account, verify the provider’s regulatory status, fees, and terms.
Frequently Asked Questions (FAQ)
What is a virtual card used for?
A virtual card provides digital payment credentials for eligible online purchases and, in some cases, in-store or recurring payments.
Is a virtual card safer than a regular card?
It may offer additional protection when it uses separate card numbers, transaction limits, or merchant restrictions. The level of security depends on the provider.
Can I use a virtual card on any website?
Not necessarily. Acceptance depends on the merchant, payment network, card type, and transaction requirements.
Do virtual cards work internationally?
Some do. International acceptance, foreign transaction fees, and currency conversion charges depend on the issuer.
Can I use a virtual card more than once?
Yes, if the product supports repeated transactions. Single-use cards are designed for more limited use.
Can virtual card details be stolen?
Yes. Virtual credentials can still be compromised through phishing, account breaches, or other forms of fraud.
Can I receive a refund on a virtual card?
Often, yes, but refund handling depends on the provider and whether the underlying account remains active.
Do virtual cards affect credit scores?
A virtual card itself does not automatically affect a credit score. If it is connected to a credit account, that account’s activity may affect credit reporting under applicable local rules.
Final Thoughts
Learning how to use a virtual card can help you better understand the payment security options available when shopping online.
Virtual cards may reduce exposure of your primary payment details and offer useful controls over spending or transactions.
However, their features vary, and they do not eliminate fraud, merchant disputes, or borrowing costs.
Before using one, compare available providers, understand the applicable fees, and review the security features included.
The safest approach combines appropriate payment technology with careful shopping decisions and responsible financial habits.
Disclaimer
This article is intended for general educational and informational purposes only. It does not constitute personalized financial, banking, security, legal, tax, or investment advice.
Virtual card availability, features, fees, payment acceptance, and consumer protections vary by country, institution, and card programme.
No payment method guarantees complete protection against unauthorized transactions, online scams, or financial losses.
This article does not endorse a particular bank or virtual card provider. Readers should confirm information with their financial institutions and applicable local authorities.
Last reviewed: November 14, 2026.